$110 Million Refinances 731 Stafford Units, and the Old Loan Has Two Sizes
Lone Star Funds took $110 million from TPG Real Estate Credit on 731 apartments at The Grid. Two sources disagree on how big the old loan was by $20 million.
By Price Per Door Staff5 min read
Capital MarketsHouston
The number
6.4%
Sugar Land/Missouri City stabilized vacancy, Q2 2026
Cushman & Wakefield, Houston Multifamily MarketBeat Q2 2026
Why it matters
Debt funds are lending on newer, well-occupied Houston apartments. A floating-rate, interest-only loan lets an owner refinance without locking in a 10-year Treasury at 5.10%.
By the numbers
- $110 million: floating-rate, interest-only loan from TPG Real Estate Credit on 731 units at The Grid in Stafford, roughly $150,479 per unit.
- 6.4%: stabilized vacancy in Cushman & Wakefield's Sugar Land/Missouri City submarket in Q2 2026, against 11.1% for metro Houston.
- 38%: alternative lenders' share of non-agency loan closings in Q2 2026, up from 34% a year earlier, according to CBRE.
- 8.04%: Trepp's September multifamily CMBS delinquency rate, up from 6.59% a year earlier.
The risk
Debt service on a floating loan follows the Fed, which raised rates in September, while Houston metro rents are down 2.0% from a year earlier.
What to watch
The Fed's next rate decision, which resets SOFR, and Trepp's October delinquency figures after September's multifamily rate reached 8.04%.
Lone Star Funds just refinanced both of its apartment communities at The Grid in Stafford with $110 million from TPG Real Estate Credit. Walker & Dunlop arranged it and announced it on October 14, calling it a floating-rate, interest-only loan.
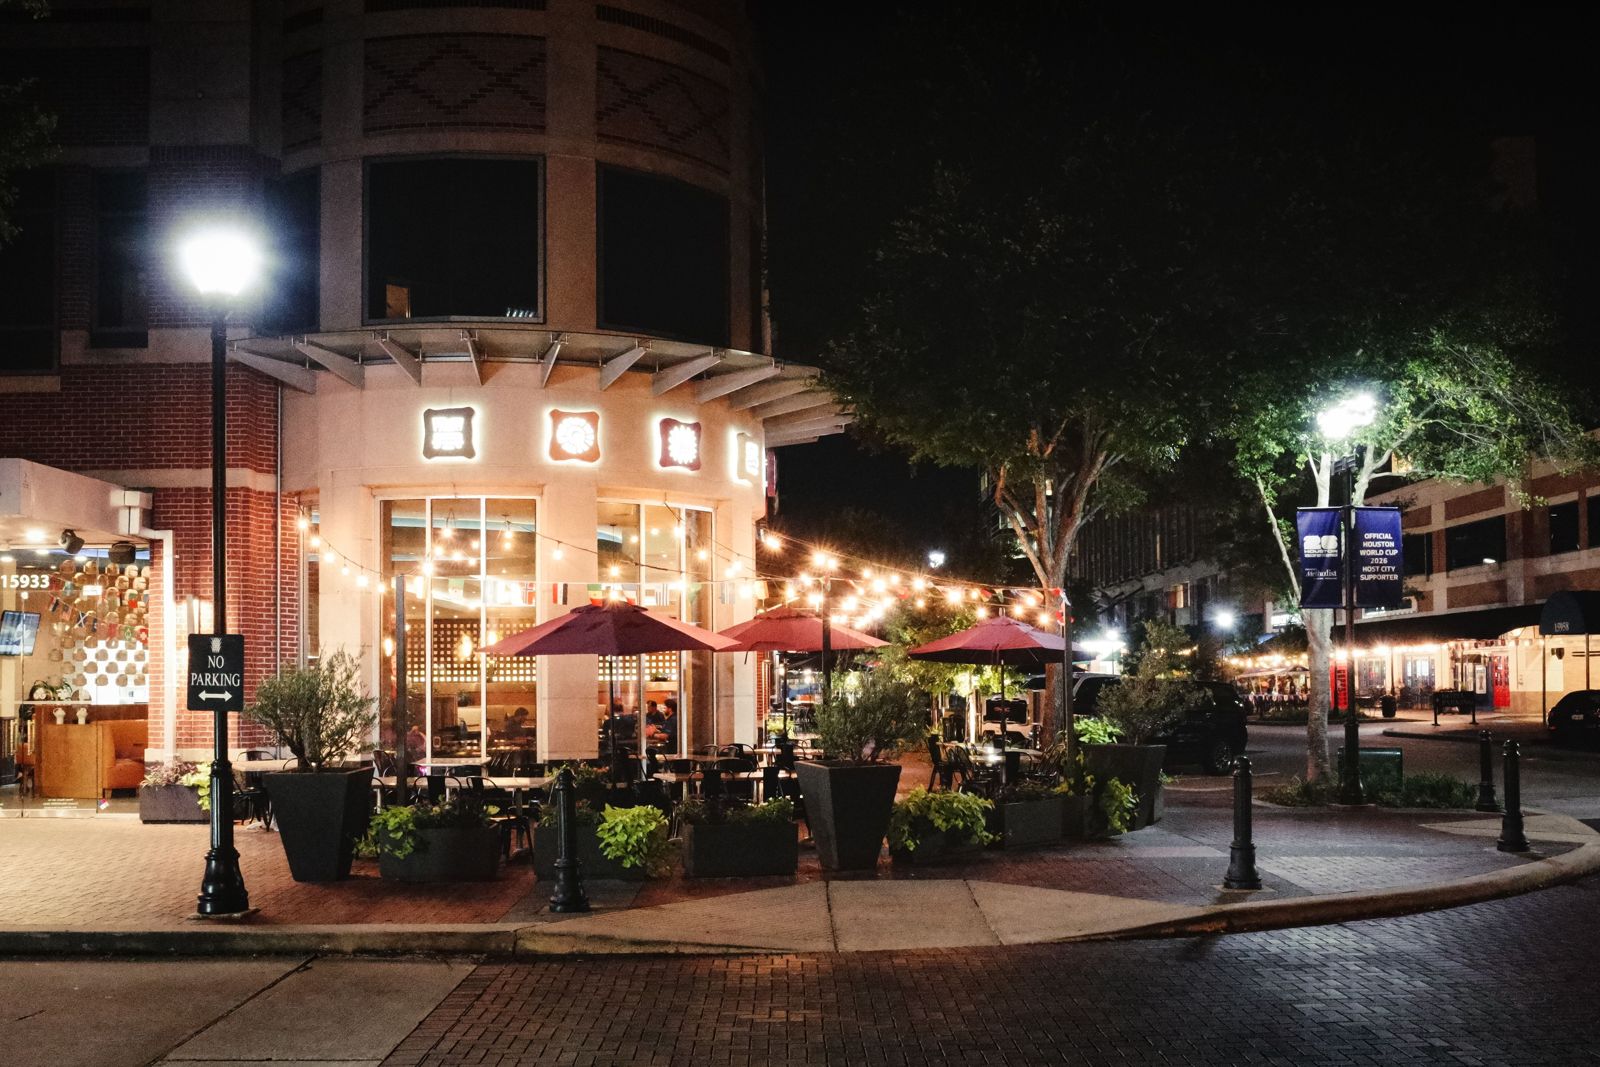
The collateral is the 385-unit 1879 at the Grid and the 346-unit Arc at the Grid, 731 apartments on the former Texas Instruments campus off West Airport Boulevard. By our arithmetic that is roughly $150,479 of debt per unit.
The release gives no rate, spread, term or loan-to-value, so the price of this money stays private.
Newsletter
Houston multifamily in 5 minutes or less
What we’re seeing on the ground in Houston: operations, market moves and the deals changing hands. Every week.
Where Texas Instruments used to make chips
Texas Instruments moved its Stafford manufacturing to Sugar Land in 2012. Bisnow reported in September 2018 that StreetLevel Investments and Provident Realty Advisors had broken ground on the site, a 192-acre, $500 million mixed-use project called The Grid.
By August 2024, Community Impact counted roughly 1,500 apartments on site and about 24 acres still to fill, with Costco and In-N-Out already open. The old TI building came down in early 2025; Commissioner Grady Prestage put the demolition cost at $2 million.
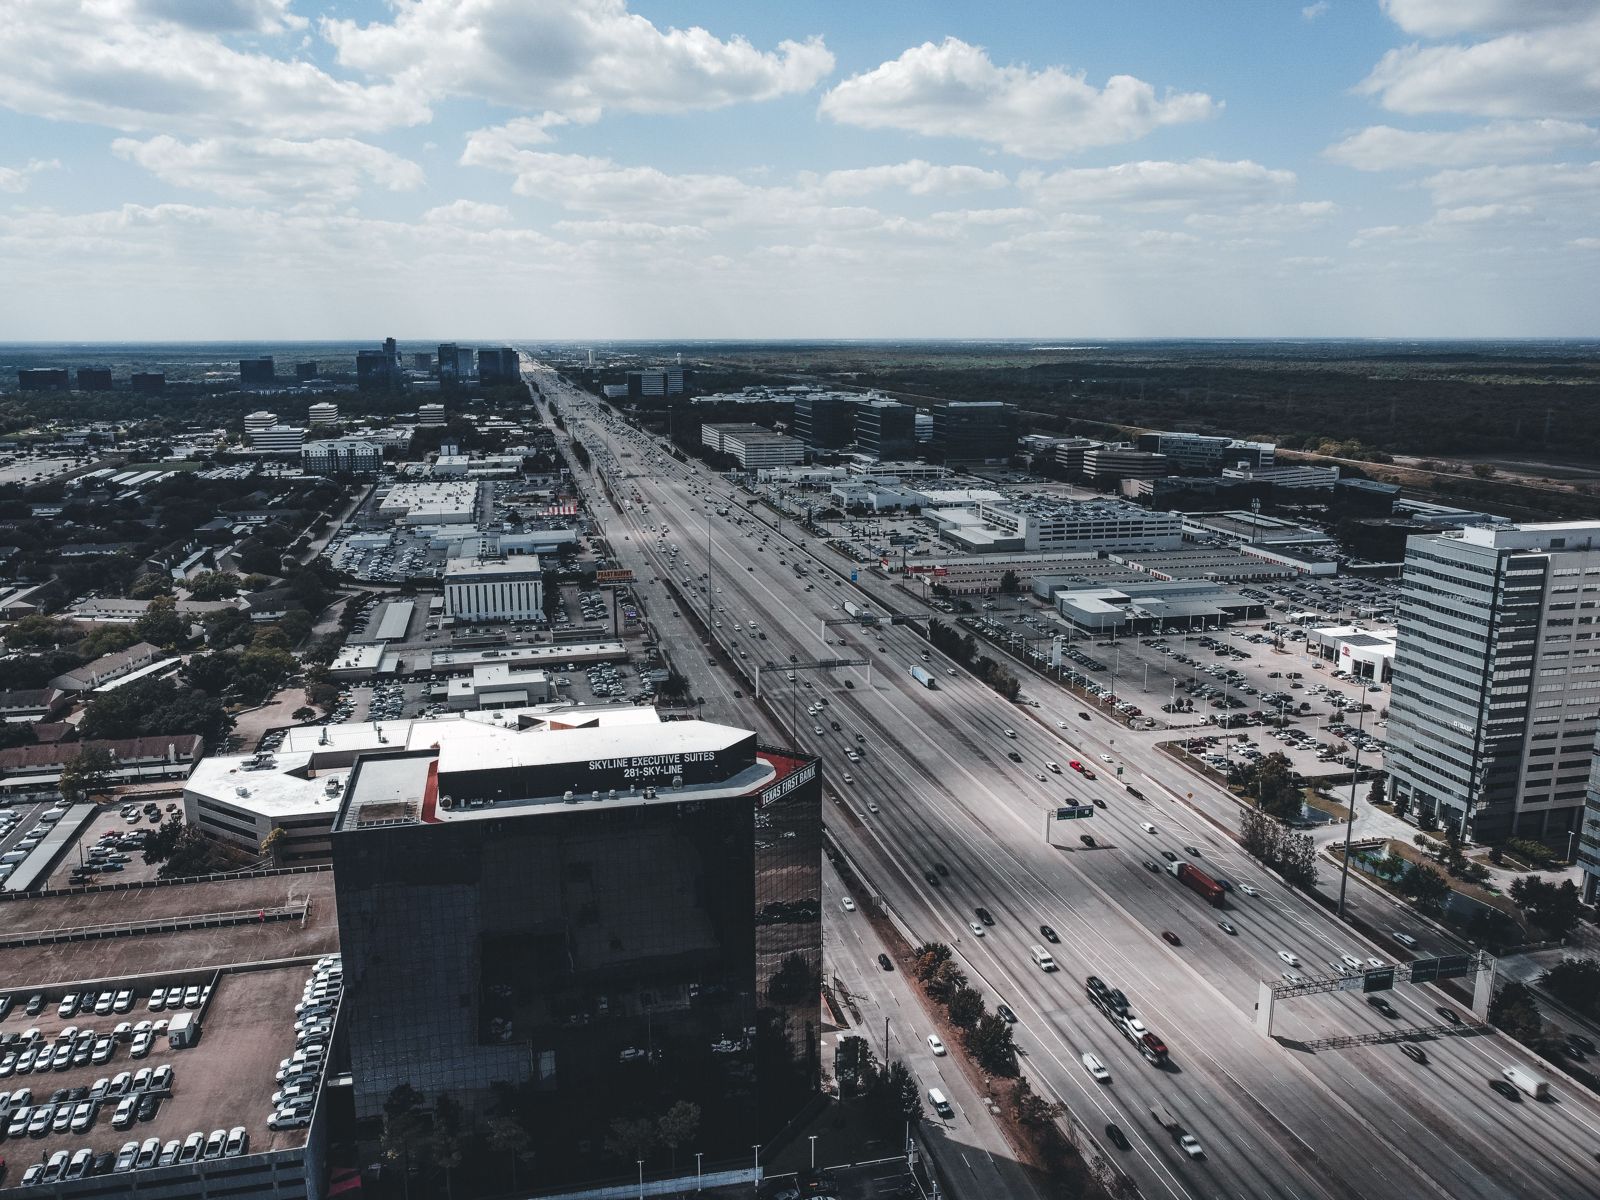
Cushman & Wakefield's Q2 2026 Houston report put stabilized vacancy in Sugar Land/Missouri City at 6.4%, against 11.1% for the metro, which makes it one of Houston's tightest.
Sugar Land/Missouri City also absorbed 961 units in the quarter, second only to Bear Creek/Copperfield.
Yardi Matrix data cited by Multi-Housing News show 1879 at the Grid at roughly 94% occupancy with an average rent of $1,692, while Arc at the Grid averages $1,754.
USAFacts, working from Census estimates, says Fort Bend County added 24,200 residents between 2024 and 2025, the eighth most of any U.S. county.
The old loan is $118 million or $98 million
Hudson Advisors, a Lone Star affiliate, bought both properties from JLB Partners in January 2022.
Last December, Lone Star sold two Irving communities totaling 673 units to KKR, according to Yardi Matrix data reported by Multi-Housing News.
Natixis announced on January 14, 2022 that it had made a $118 million floating-rate acquisition loan. Multi-Housing News, citing Yardi Matrix, now puts that loan at $98 million.
Against $118 million, the new loan is $8 million smaller, which would imply the sponsor paid down debt at closing; against $98 million, it is $12 million larger.
The Natixis release also says the two communities total 931 units, though 346 plus 385 is 731. Neither source explains the gap, and we could not resolve it before publication.
Why a debt fund said yes
CBRE said on August 3 that alternative lenders, a group that includes debt funds, made 38% of non-agency loan closings in Q2 2026, up from 34% a year earlier, while CMBS slipped to 11% from 19%.
CBRE also had multifamily spreads at 162 basis points, 15 tighter than a year before, and average multifamily loan-to-value at 63.3%.
Walker & Dunlop said its capital markets team placed more than $13.9 billion with non-agency lenders in the first half of 2026, nearly $9.6 billion of it on multifamily.
The MBA's second-quarter survey points the same way: originations by investor-driven lenders rose 18% from a year earlier, while GSE volume fell 17%.
The Federal Reserve raised its target range a quarter point to 3.75% to 4.00% on September 16, and the New York Fed published SOFR, the usual index for floating loans, at 3.89% on October 15.
Treasury data show the 10-year yield, which sets fixed-rate pricing, at 5.10% on October 15, down from 5.31% on October 5. A floating loan avoids locking in a long-term rate at that level, and interest-only terms keep principal payments off the cash flow while the loan is outstanding.
What it means for owners and investors
Trepp's Stephen Buschbom told CRE Daily in April that Houston made up about 30% of delinquent multifamily CMBS balances, and Trepp put the national multifamily CMBS delinquency rate at 8.04% in September, against 6.59% a year earlier.
Bank balance sheets look calmer. CRED iQ put the delinquency rate on bank-held multifamily loans at 1.41% in Q2 2026, down from 1.47% in the first quarter.
The Grid buildings sit far from that distress: newer Class A stock in a submarket with 6.4% vacancy. Walker & Dunlop's Dustin Stolly credited the growth of the Stafford and Sugar Land corridor when he explained why TPG Real Estate Credit took the loan.
Owners of older or emptier properties face a harder market. The MBA counts $875 billion of commercial mortgages maturing in 2026, and Gantry's Charlie Kokernak wrote in Multi-Housing News on October 14 that bridge lenders' higher costs, reserves and repayment terms have to be measured against a realistic exit.
Apartment List's October report has the Houston metro median at $1,335, down 2.0% from a year earlier, and CRE Daily reported on October 13 that RealPage expects 0.5% Houston rent growth over the next four quarters.
Job growth is slow as well: the Dallas Fed counted 0.5% Houston payroll growth from July 2025 to July 2026, with unemployment at 4.9%.
On supply, Northmarq expects about 5,600 Houston deliveries in 2027, which would be the lowest annual total in nearly 15 years.
Northmarq also says Houston cap rates have generally ranged between 5.5% and 6.5% in 2026, a thin margin over a 10-year Treasury at 5.10%.
What to watch next
SOFR tracks the Fed, so the next rate decision sets the interest bill on these 731 units.
Trepp said five large single-asset, single-borrower loans drove much of September's overall increase in delinquency. Its October figures will show whether the multifamily rate keeps climbing without help from loans that size.
Closer to home, Lenox at the Grid opened 350 units on the same campus in 2024, so these two properties already have a newer competitor next door.
Sources
- Walker & Dunlop: $110 million refinancing for two multifamily properties in Stafford
- Multi-Housing News: Lone Star refis Houston multifamily properties for $110M
- Cushman & Wakefield: Houston Multifamily MarketBeat, Q2 2026
- CBRE: Commercial real estate lending fundamentals, Q2 2026
- Northmarq: Houston multifamily vacancies trend lower at midyear
Written by Price Per Door from public reports, filings and data. See all sources.